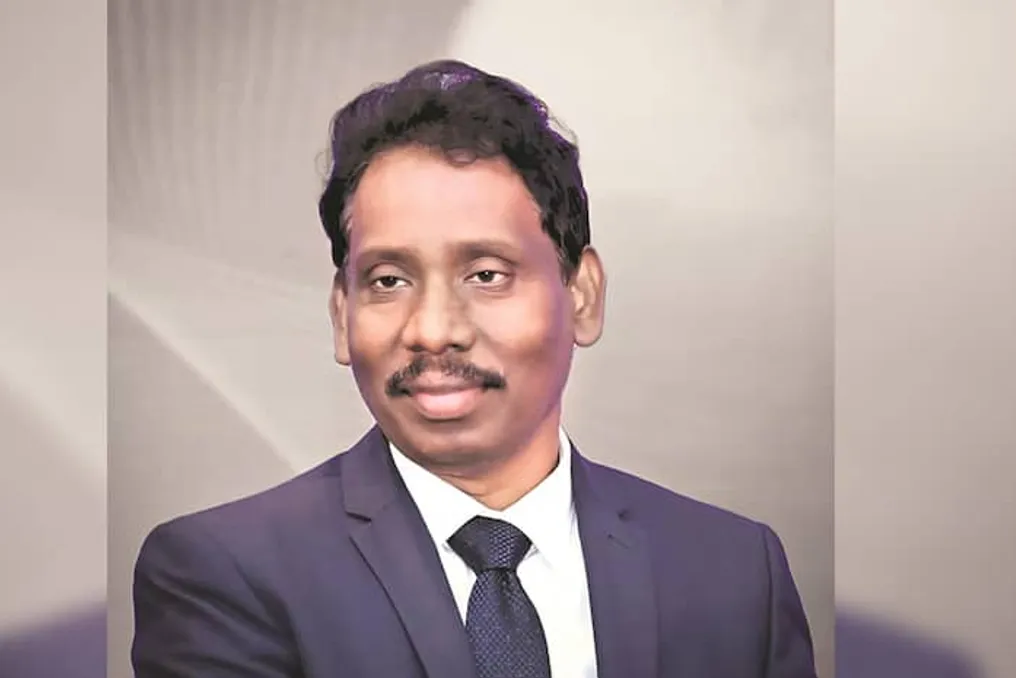
Deputy Governor of the Reserve Bank of India (RBI) S. S. Murmu emphasized that instances of incorrect financial product sales are most often due to the variable pay system and set targets, rather than the actions of employees in bank branches. He strongly urged financial institutions to thoroughly analyze their incentive systems to determine whether they reward sales volume or customer-centric results, as well as how these metrics are measured.
During the XIth Annual Governance Summit in Mumbai, Murmu noted that the issue of incorrect sales remains relevant for India's financial sector, particularly in the distribution of insurance policies, mutual funds (MF), and other third-party products through banks and financial organizations.
Furthermore, Murmu drew attention to significant regulatory changes awaiting banks starting April 1, 2027, when the new prudential framework will come into effect. This transition will include the implementation of Expected Credit Loss (ECL) provisioning, the realization of remaining Basel III standards, and the adoption of a new standardized approach to credit risk.
Under the ECL framework, banks will be required to provision for anticipated losses instead of only accounting for losses that have already occurred. This new structure will replace the existing loss-based provisioning approach. According to the new norms, banks will classify financial assets into three stages based on changes in credit risk and provision accordingly. Stage one assets will require provisions for expected credit losses over 12 months, while stage two and three assets will require provisions for expected credit losses over the entire term.
Murmu stated that these changes will increase the sensitivity of the banking system to risks and place greater responsibility on the boards of directors. When transitioning to principle-based regulation, boards of directors will have more freedom in determining their institution's risk appetite. However, this will also increase their obligation to clearly define this appetite in both qualitative and quantitative terms, and to hold management accountable for adhering to this appetite.
The Deputy Governor also stressed the critical importance of investments in technology and personnel, noting that for financial institutions, this is no longer an optional element. Boards of directors must understand exactly how technology is used and what risks are associated with it.
He also mentioned changes in RBI directives for banks that came into force on October 1, 2026. The revised directives replaced board agendas based on checklists with principle-based guidelines, eliminating a long list of prescribed routine items. This will free up board time, which leaders can dedicate to strategic issues and risks, including technological risks, and ensure readiness for the transition to the new prudential framework in April 2027.
Murmu called for closer coordination among financial sector regulators, given the overlap of their mandates. For instance, a listed bank falls under RBI's prudential norms and guidelines on related party lending, as well as SEBI India's listing regulations governing related party transactions. He added that cyber resilience requires common baseline standards, as one incident could simultaneously affect a bank, an insurer, and a market infrastructure institution.
In conclusion, he stated: 'Regulation does not succeed by writing rules faster. It succeeds by clarifying expectations from those who manage and oversee institutions, and then trusting their judgment.'