Analysts believe large-cap stocks are regaining strategic leadership amid market uncertainty
Read more
Business Standard
business-standard.com

Analysts believe large-cap stocks are regaining strategic leadership amid market uncertainty

Despite significant selling pressure from foreign institutional investors (FII), which has long negatively impacted Indian stocks, a shift in trends is being observed. Analysts note that after mid and small-cap stocks led the market growth for most of 2026, they are beginning to lose momentum, while large-cap stocks are demonstrating greater resilience amidst growing market uncertainty.

According to a note from Bajaj Broking dated November 2, large-cap stocks appear better suited for achieving superior risk-adjusted returns over the next six to eighteen months. This is attributed to the maintenance of relatively stable fundamental metrics, increased attractiveness of their valuations, and persistent liquidity advantages.

Listen to this article

Payal V. Pandya, Vice President of Prive-Research at Bajaj Broking, asserts that strong domestic institutional flows, ample liquidity, and sustained risk appetite supported mid and small-cap stocks for most of the year. However, the situation began to change during the festive season around September 11, when blue-chip stocks significantly outperformed their mid and small-cap counterparts.

Between September 11 and November 2, 2026, the Nifty 50 index fell by only 0.5 percent, whereas Nifty Midcap 100 lost 7 percent, and Nifty Smallcap 100 lost 6.6 percent. Pandya observes that this divergence indicates a developing preference among increasingly cautious investors for quality, liquidity, and greater earnings predictability.

The note emphasizes that while mid and small-cap stocks drove the market for most of the current cycle, the recent divergence suggests that investors are placing greater value on valuation discipline, revenue visibility, and downside protection. The question arises whether the risk-reward balance is shifting towards large-cap companies, or if they can simply outperform other segments at any market phase.

This shift occurs against a backdrop of numerous factors clouding market prospects, including the implications of upcoming US midterm elections, corporate earnings trajectories, geopolitical tensions, and the overall global economic growth outlook. Nevertheless, Pandya believes that in the coming quarters, large-cap stocks may offer investors greater stability. Although they may not deliver the sharpest gains during periods of abundant liquidity and aggressive risk-taking, their scale, stronger balance sheets, and relatively predictable earnings make them attractive as market volatility increases.

Furthermore, Bajaj Broking believes that the valuations of these stocks are becoming increasingly reasonable compared to historical levels, strengthening the investment case for this segment.

FII Selling

Selling by foreign institutional investors (FII) remained a significant hurdle for Indian stocks in the recent market cycle. However, this pressure also affected some heavyweights in the large-cap index, including companies that continued to show healthy operational results.

Pandya suggests that this could create an opportunity if global risk appetite improves, geopolitical uncertainty subsides, or India attracts additional foreign investment. According to the note, the most likely beneficiaries of a recovery in foreign flows will be large-cap stocks, particularly those in the Nifty 50, leading private banks, and major financial service companies. Their advantage over mid and small-cap stocks lies in deeper liquidity, larger market capitalization, and the ability to absorb substantial institutional investment.

Pandya concludes that the investment potential of large-cap companies is increasingly focused on their ability to withstand market volatility rather than delivering impressive short-term returns.
Similar stories

Evolution of Long-Term Capital Gains Taxation on Stocks in India: A Chronology of Changes Since 2003
Read more
business-standard.com

Evolution of Long-Term Capital Gains Taxation on Stocks in India: A Chronology of Changes Since 2003

The policy regarding Long-Term Capital Gains (LTCG) from stock investments in India has undergone numerous significant changes, moving from temporary exemption in 2003 to a tax-free regime in 2004, followed by the reintroduction of taxes in 2018 and current calls for reform.

Reuters reported on Monday that the Securities and Exchange Board of India (Sebi) recommended to the government the abolition of the Long-Term Capital Gains (LTCG) tax for Foreign Portfolio Investors (FPIs). Furthermore, the market regulator proposed tax incentives for domestic mutual fund investors who sell their current assets to reinvest in other schemes.

These recommendations emerged against a backdrop of sustained outflow of foreign investors and growing concern over the tax burden associated with stock investments. The government has not yet adopted these proposals.

The history of taxation shows how it has evolved: from abolition in 2004 to reintroduction in 2018 and a subsequent increase in the rate in 2024.

Before 2003: LTCG Tax Was Applicable

Prior to the introduction of the exemption in 2003, long-term capital gains from listed stocks were taxed according to the Income Tax Act, under applicable provisions and rates. The tax regime depended on the nature of the security and the investor. Foreign Institutional Investors (FIIs), an earlier regulatory category for overseas portfolio investors (merged with FPIs in 2014), were also subject to capital gains tax under applicable provisions.

February 28, 2003: Temporary LTCG Exemption Introduced

Finance Minister Jaswant Singh announced in the 2003-04 Union Budget a temporary exemption for listed stocks acquired on or after March 1, 2003, and sold after holding them for at least one year. The purpose of this exemption was to stimulate capital markets and encourage stock investment.

July 8, 2004: Abolition of LTCG Tax Declared

Under the new UPA government, Finance Minister P Chidambaram announced a larger change in the 2004-05 Union Budget. He proposed to completely abolish the LTCG tax on securities transactions and replace it with Securities Transaction Tax (STT) on stock exchange trades. The proposed STT rate was 0.15 percent of the security value, payable by the buyer. The government also proposed reducing the short-term capital gains tax rate on securities to a fixed 10 percent. The new system came into effect on October 1, 2004. Section 10(38) of the Income Tax Act provided an exemption for qualified long-term gains from listed stocks, provided the sale transaction was subject to STT.

2017: Tightening of Exemption Conditions

The tax-free regime came under scrutiny after concerns arose that some investors were using it to conceal untaxed funds in the form of tax-free capital gains. To address this issue, the Finance Act of 2017 amended Section 10(38) of the Income Tax Act. Under the revised rules, investors acquiring stocks after October 2004 could generally claim LTCG exemption only if STT was paid both at the time of purchase and at the time of sale. In June 2017, the Central Board of Direct Taxes (CBDT) issued a notification listing transactions exempt from the additional STT requirement, provided certain guarantees were met.

February 1, 2018: Reintroduction of LTCG Tax

Finance Minister Arun Jaitley announced the return of the LTCG tax on listed stocks in the 2018-19 Union Budget, ending a 14-year period of tax exemption. The government proposed a tax of 10 percent on annual long-term capital gains exceeding 1 lakh rupees. Unlike some other capital gains provisions, investors did not benefit from indexation, which adjusts the asset's purchase price for inflation when calculating taxable gains. A new Section 112A was introduced to bring back long-term gains from listed stocks, equity-oriented mutual funds, and business trust fund units into the tax net. The new tax structure became effective from April 1, 2018, for the financial year 2018-19. Qualified long-term gains exceeding 1 lakh rupees from listed stocks, equity-oriented mutual funds, and business trust fund units were taxed at a rate of 10 percent under Section 112A. The exemption continued to depend on STT requirements. Unlike the previous tax-free regime, investors now had to pay both STT on applicable transactions and income tax on qualified long-term gains above the annual threshold.

July 23, 2024: Increase in LTCG Tax to 12.5 Percent

Finance Minister Nirmala Sitharaman increased the LTCG tax rate for qualified listed stocks from 10 percent to 12.5 percent in the 2024-25 Union Budget. Simultaneously, she raised the annual exemption threshold from 1 lakh rupees to 1.25 lakh rupees. These changes took immediate effect, applying to transactions made on or after July 23, 2024. The budget also raised the short-term capital gains tax rate for qualified listed stocks, equity-oriented mutual funds, and business trust fund units subject to STT, from 15 percent to 20 percent.

2026: Return of Calls for LTCG Relief in Political Debates

The discussion about the tax burden of stock investments resurfaced amid concerns about the outflow of foreign portfolios and the relative attractiveness of Indian markets. On July 20, 2026, the government informed the Lok Sabha that no proposals to abolish the LTCG tax on stocks were being considered. Finance Minister Pankaj Chaudhary also stated that the 12.5 percent rate applies equally to domestic retail investors and FPIs. On November 2, Reuters reported that Sebi recommended abolishing the LTCG tax for foreign investors and also suggested that domestic mutual fund investors should not pay LTCG tax when switching between schemes after holding units for more than a year.

Share of foreign investors in Indian real estate declined; the market now relies on domestic investors
Read more
www.aajtak.in

Share of foreign investors in Indian real estate declined; the market now relies on domestic investors

Private capital investments in Indian real estate have faced a significant downturn. In the first nine months of 2026, investments in the sector decreased by 31% year-on-year, amounting to $1.66 billion, compared to $2.41 billion during the same period last year.

Despite the overall decrease in investment volume, the number of deals increased from 24 to 31, indicating growing investor activity. However, there was a shortage of large transactions.

According to a report by the consulting firm Knight Frank India for the third quarter of 2026, the share of Indian investors has significantly risen. If in the first nine months of 2025, domestic investors accounted for 25% of the total private investment, this figure reached 85% in the same period of 2026. Consequently, the share of foreign investors fell from 75% to 15%.

The report indicates that in the first nine months of 2026, private capital investments in real estate reached the lowest level in the last six years. The main reason for this was the lack of large deals. The average size of a listed deal also decreased by 47%, reaching $530 million, compared to nearly $1 billion the previous year. In the third quarter of the year (July-September 2026), a decline in real estate investment was also recorded, amounting to 43% year-on-year, or $530 million. Meanwhile, the number of deals grew from 12 to 15, highlighting the drop in total funds despite an increase in transactions.

Among various real estate segments, office properties remained a priority choice for investors. From January to September 2026, $1.18 billion in private investments flowed into the office segment, accounting for about 71% of the total. Nevertheless, investments in office real estate decreased by 19% compared to the same period last year. The largest portion of investments in the office segment was directed towards ready-to-move properties, which accounted for 78% of the total, up from 49% last year. Furthermore, 88% of the capital in the office segment was invested through equity. The increased interest in ready-to-move office properties is attributed to easier assessment of potential rental income and reduced risks associated with construction, unlike projects under construction where delays and cost overruns are risks.

Private capital investments in residential real estate also decreased. From January to September 2026, $320 million flowed into this segment, which is 33% less than the $480 million recorded in the same period last year. Notably, 97% of these funds came through debt financing and structured loans, rather than directly through equity. 83% of investments in the residential segment were directed towards projects under construction. In the third quarter, approximately $190 million entered the residential real estate market, making up about 60% of the total investment in the first nine months. According to the report, 63% of all residential real estate investments were directed to the NCR, demonstrating a strong presence of investors in the Delhi-NCR housing market.

Investment trends in the warehousing segment differed from the rest of the market. In the first nine months of 2026, $160 million flowed into this segment, a 66% increase compared to $100 million during the same period last year. However, the entire volume of investment in warehousing was executed within a single deal related to a ready asset. In contrast, no private capital deals were registered in the retail real estate segment from January to September 2026, although about $374 million was invested in this segment last year.

From a city perspective, the NCR became the main hub for private capital investment in real estate from January to September 2026. $568 million was invested in the NCR, accounting for about 34% of the total investment in the country. Last year, the NCR's share was only 9%, with investments around $210 million. Pune saw investments of $356 million, accounting for 21% of the total. Chennai received $319 million, securing a 19% share. Investments in Mumbai amounted to $276 million, while in Bangalore they decreased to $137 million. Hyderabad saw investments of approximately $40 million, and no investments were recorded in Kolkata.

According to Knight Frank, domestic investors channeled a total of $1.42 billion into Indian real estate from January to September 2026, representing about 85% of the total private investment. Last year, the contribution of domestic investors was about $603 million, or 25% of the total. Domestic investors provided 94% of the investments in the residential segment and 81% of the investments in the office segment. Additionally, domestic capitalization participated in the sole transaction in the warehousing segment.

Fund managers assert that value investing is relevant, but stock selection is the key factor
Read more
business-standard.com

Fund managers assert that value investing is relevant, but stock selection is the key factor

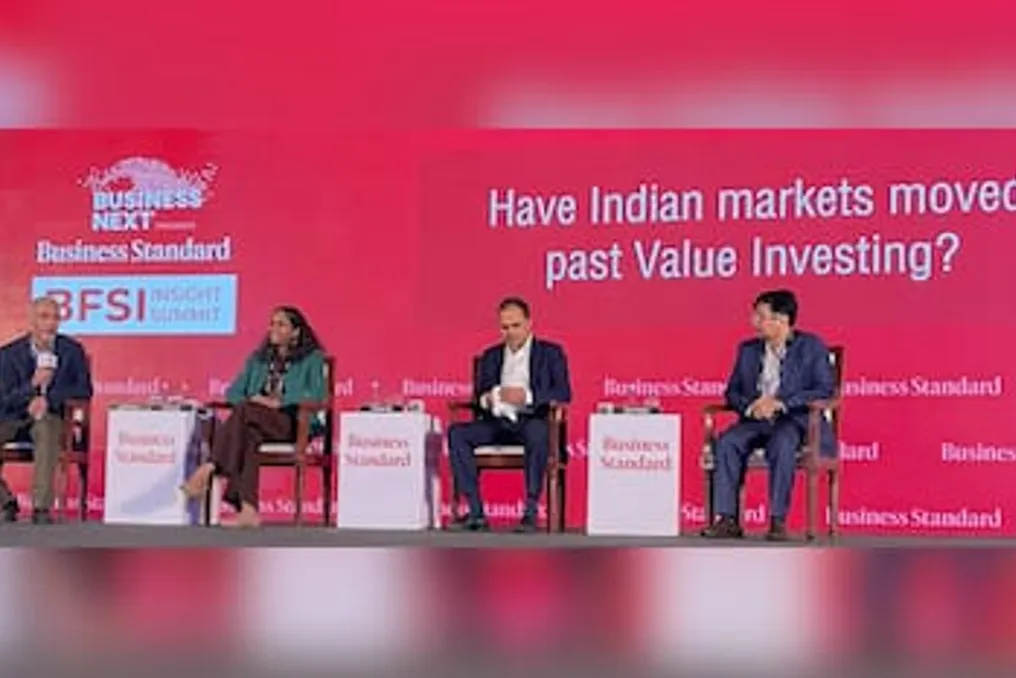
Fund managers stated at the Business Standard BFSI Summit in Mumbai that value investing remains significant in Indian markets. However, investors must be able to distinguish between stocks that are genuinely undervalued and those whose business prospects are deteriorating.

During a session moderated by Parin Palande from Business Standard, Rajiv Takkar, Director of Equity Investments and Head of PPFAS Asset Management, noted that investments should be based on comparing a company's intrinsic value with its market price, rather than applying labels such as 'value' or 'growth.'

Takkar cited an example of investing in American technology stocks where, in his opinion, the market did not reflect their true value, allowing them to be assessed using traditional methods. He explained that the difference between value and growth investing often depends on how heavily investors rely on future earnings. Growth investors tend to derive most of the company's value from cash flows expected many years later, whereas value investors prefer a clearer view of short-term cash flows.

He warned that overly long-term forecasting can make valuations vulnerable to errors, referencing the experience of Indian technology stocks. Furthermore, Takkar advised investors not to ignore corporate governance when seeking profits. Although governance standards have improved due to regulatory changes, disclosure requirements, and digital transactions, he believes investors can be overly lenient towards promoters with questionable histories.

Patience, conviction, and research

Prashant Jain, Founder and CIO of 3P Investment Managers, emphasized that holding an investment for a long period of low returns requires a deep understanding of the company's operations and the reasons why the market values it as it does. Jain stated that investing is more related to emotional intelligence (EQ) than intellectual intelligence (IQ), and such conviction must be supported by thorough research and a complete understanding of the business.

He also recounted his decision to exit the Indian technology sector in November 1999 when valuations were high, as he considered the sector's growth rates at that time unsustainable. Nevertheless, he does not see this sector losing relevance, noting that Indian technology companies continue to show positive revenue growth in dollars despite deflationary pressure that artificial intelligence might create.

AI and value seeking

Lakshmi Iyer, President of the Investment Group and CEO of Bajaj Alternate Investment Fund Managers, suggested that value investing applies to all asset classes, including fixed income. For a fund manager, the decision comes down to where the next increase in income is likely to come from—this could mean increasing investments in bonds or stocks, depending on the market cycle and the relative attractiveness of available opportunities.

Speaking about AI, Iyer noted that India's investment landscape in this area differs from the US, where most spending is directed towards building basic infrastructure and developing large language models. Activity in India, she said, has been more focused on applications. She does not consider the opportunities in AI in India to be in a bubble, as local companies have not relied on the large-scale borrowing seen in some foreign AI investments, but have mainly financed capital expenditures through cash flows.

However, regarding listed Indian technology companies, Iyer expects investors to become more selective. She cautioned: 'Everything sold at a discount does not necessarily offer value,' adding that investors must determine whether a correction reflects a temporary downturn or a sustained deterioration of the business condition.

Large companies offer relative value

Takkar observed that large-cap stocks generally trade at lower valuations compared to mid- and small-cap stocks. Referring to Price-to-Earnings ratios across indices, he pointed out that Nifty 100 is around 18–19 times earnings, Nifty Midcap 150 is at 24–25 times, and Nifty Smallcap 250 is at 31–32 times. He also noted the inflow of domestic funds into the mutual fund category for mid- and small-cap companies, even when large funds recorded outflows in some months, observing that investors seem to be over-concentrating on small stocks.

Takkar reported that the top 100 companies generate an estimated 65–70 percent of the profit generated by the leading 500 listed companies in India. This concentration of earnings underscores the importance of investors not ignoring larger enterprises just because their stocks have lagged. Jain agreed that the market may experience a mean reversion, and the relative dynamics of different segments may change over time. However, he cautioned against a uniform approach to all small and medium-sized companies. He stressed: 'There is value, there is stability, there is growth in large companies, and they cannot be ignored.' He added that smaller companies can also provide stock-picking opportunities, but investors need to be selective and conduct targeted research.

Iyer advocated for a balanced approach instead of completely abandoning any segment. She recommended that investors look beyond index movements and market narratives to find companies with solid fundamentals and reasonable valuations.

Popular