Finance Minister emphasizes priority of insurance for all in financial inclusion agenda
Read more
Business Standard
business-standard.com

Finance Minister emphasizes priority of insurance for all in financial inclusion agenda

Finance Minister Nirmala Sitharaman stated that the government will focus efforts on expanding coverage with insurance and pension schemes, improving access to credit, AI training, and conducting banking reforms to stimulate financial inclusion.

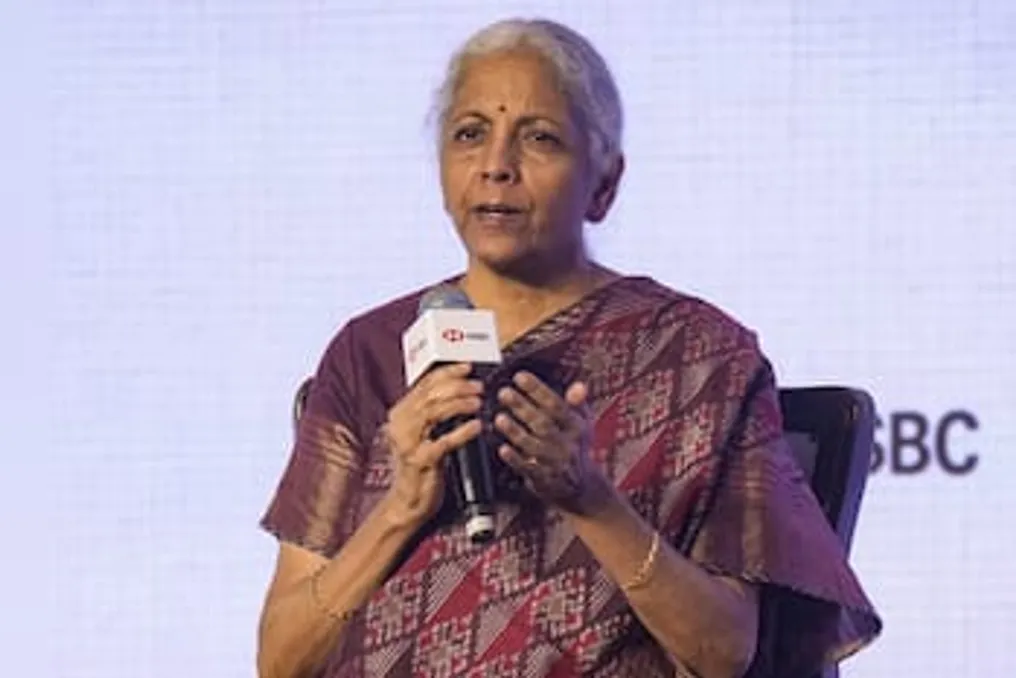
'Insurance for all' will be a key focus in the government's financial inclusion agenda. The ministry aims to increase access to insurance and pension schemes, especially among the least affluent segments of the population, announced Finance Minister Nirmala Sitharaman on Monday. The government is also prioritizing broader access to credit and plans to establish AI training centers in every district to bridge the gap between industry requirements and youth skills.

At the 'Algorithm of Inclusion' event in Mumbai, organized by HSBC, Sitharaman noted that public insurance and pension programs will continue to play a vital role in providing financial protection to vulnerable groups in society. Schemes such as Pradhan Mantri Jeevan Jyoti Bima Yojana and Pradhan Mantri Suraksha Bima Yojana offer insurance coverage at minimal contributions, while state-subsidized pension programs are intended for those unable to work. The minister emphasized the government's commitment to ensuring that every needy person is covered by these schemes.

The government's emphasis on expanding insurance coverage aligns with the vision of the Insurance Regulatory and Development Authority of India (IRDAI) to achieve 'Insurance for all by 2047'. This initiative aims to guarantee every citizen access to adequate life, health, and property insurance, and to cover businesses against relevant risks. The regulator is focusing on enhancing the accessibility, convenience, and affordability of insurance products, particularly in underserved and rural areas. Initiatives within this effort include Bima Sugam, a proposed digital insurance marketplace, Bima Vistaar, a combined insurance product, and Bima Vahak, a last-mile distribution network with a focus on women.

Another priority is ensuring access to formal credit, especially for individuals looking to start or expand their businesses. Furthermore, the government is working to address the mismatch between the skills of young people entering the workforce and the needs of employers. Sitharaman stated that the ministry wants there to be an AI training center in every district, allowing youth to acquire industry-relevant skills closer to home.

The government will also support states in modernizing Industrial Training Institutes (ITIs), many of which lag behind changing industry demands. The ministry will provide funding, and states can identify leading trainers.

Regarding the banking sector, Sitharaman reported that the government will form a high-level committee to study future sector needs and develop recommendations for strengthening the Indian banking system. Although Indian banks have recovered from the difficulties of 2014–2015, the sector must continue to evolve to meet the demands of a growing economy. The committee will consult with industry participants and experts before presenting its findings.

The Ministry of Finance announced last week that the chairman of the committee will be Suresh N Patel, former Central Vigilance Commissioner (CVC), who has over thirty years of experience in the banking sector. Patel held positions as CEO and Executive Director of Andhra Bank and Oriental Bank of Commerce. The committee includes Shirish Chandra Murmu, Deputy Governor of the Reserve Bank of India (RBI), Padmaja Chundru, former Managing Director and CEO of Indian Bank, and N. S. Vishwanathan, former Deputy Governor of the RBI. The committee secretary will be the Joint Secretary (Banking) of the Department of Financial Services. According to the Ministry of Finance statement, the committee has six months to complete its work, until April 2027.

Explaining the resilience of the Indian economy amid global uncertainty, the finance minister linked it to strong domestic demand, rising purchasing power, and policy stability. She noted that growth in domestic consumption is being observed due to the large domestic market and the rising purchasing power of the middle class. While exports remain important, the expansion of the domestic market has added extra strength to the economy.

Sitharaman also attributed the decline in poverty levels to a combination of social security measures and improved access to healthcare, education, food security, and financial services. Medical coverage under the Ayushman Bharat scheme, which provides up to 5 lakh for treatment to eligible families, has helped protect households from high out-of-pocket healthcare expenses. Such expenses often force rural families to sell land and other assets to pay for treatment. Additionally, free grain distribution programs, housing, sanitation, and water supply initiatives have contributed to improved living conditions.

The finance minister also stressed the need to maintain fiscal discipline while simultaneously increasing government spending to support economic growth. Capital expenditure has significantly increased over the last four to five years, and the multiplier effect has also grown. She stated that the government will continue to support growth through capital expenditure while maintaining fiscal responsibility so that India's growth momentum does not slow down.
Similar stories

Sicredi expands financial guidance for members through digital platform
Read more
g1.globo.com

Sicredi expands financial guidance for members through digital platform

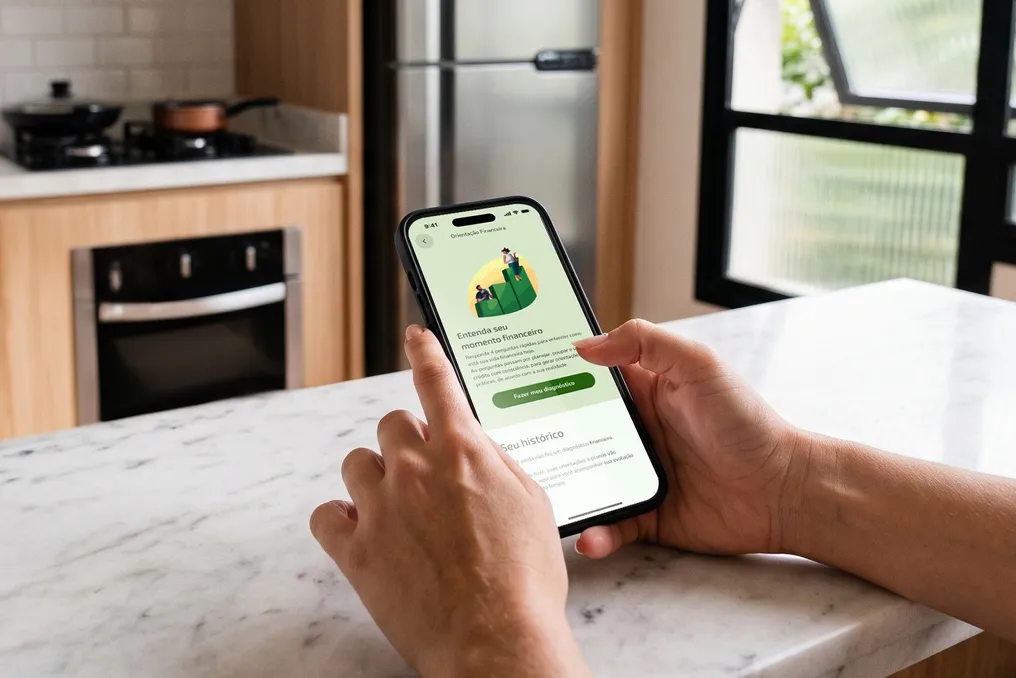
Sicredi has implemented its Financial Guidance initiative in the digital environment, aiming to increase support for its members both in managing their finances and in making more conscious decisions. This experience offers detailed analyses and personalized suggestions on topics such as investments, planning, and responsible credit use, accessible via the Sicredi X application, which has been progressively adopted by the members of this financial cooperative.

Previously, Financial Guidance was provided through business manager advice at Sicredi branches and via remote channels, such as WhatsApp, helping members reflect on their economic situation and define action plans according to their goals and needs. The recent addition of this initiative to the digital environment has already accumulated over 140 thousand services and reached members across the entire national territory.

How it works

The digital process begins with a questionnaire consisting of four questions, focused on how the member organizes their finances, their ability to manage unforeseen events, and their relationship with financial obligations. Based on these answers, the system determines which area requires the most focus at the moment: whether it is financial planning, savings, or conscious credit.

Subsequently, the member receives a tailored plan and can select between two or three practical actions to implement. Recommendations include educational materials, such as videos, courses, and financial organization tools. Furthermore, the journey integrates products and services from an educational perspective, explaining simply how each solution can contribute to financial well-being. The user also has the option to monitor their progress, access past guidance, and redo the diagnosis whenever there is a change in their financial condition.

Machado commented that very positive results have been observed among those who used Financial Guidance, whether in person or remotely. He highlighted the adoption of healthier financial habits and the strengthening of the bond with Sicredi. According to him, with this initiative, the institution reaffirms its commitment to supporting more thoughtful financial choices and generating lasting value for members and the communities where it operates. He emphasized that financial well-being is a continuous process, and access to appropriate information and guidance is crucial to converting intention into action.

To strengthen financial well-being, the new digital tool was created to help members analyze their financial life and identify opportunities for improvement in a practical and personalized way. Some daily practices can support more conscious decisions:

  • Know your financial reality: Constantly monitor income, expenses, and commitments to understand money usage and find opportunities for improvement.
  • Have an emergency reserve: Maintaining a financial reserve provides greater security to deal with unexpected events without harming the budget or long-term plans.
  • Define clear goals: Setting goals provides direction to financial decisions and facilitates maintaining discipline over time.
  • Use credit consciously: Before taking on new debts, it is essential to evaluate the real need, the repayment capacity, and the impact of the decision on the budget.
  • Review habits periodically: Since financial planning is a continuous cycle, reviewing expenses, priorities, and goals helps keep finances aligned with different life stages.
Expert claims fiscal discipline and infrastructure reform can stimulate investment in South Africa
Read more
iol.co.za

Expert claims fiscal discipline and infrastructure reform can stimulate investment in South Africa

Corporate finance expert Jason Hamilton believes that South Africa needs to strengthen fiscal discipline, reliable infrastructure, and stable policies to attract private investment and create jobs. He put forward these theses ahead of the presentation by the Ministry of Finance of Enoch Godongwana of the Medium-Term Budget Policy Statement (MTBPS).

Hamilton, who teaches corporate and development finance courses at Stellenbosch Business School, emphasizes that before companies decide to expand or hire staff, they require greater certainty regarding government spending, infrastructure project implementation, and economic reforms.

According to Hamilton, when Godongwana presents the MTBPS on Wednesday, businesses will seek a clearer foundation for making investment decisions. This applies to small businesses considering hiring new employees as well as large corporations weighing major expansion plans. Investment decisions depend on numerous factors, including the state of public finances, infrastructure reliability, policy consistency, and confidence in fulfilling commitments, which affects available financing and required returns.

The expert insists that more attention should be paid to the gap between policy announcement and the moment when businesses can start acting according to it. In February, the National Treasury projected the stabilization of gross public debt at 78.9% of GDP in 2025/26, followed by a decrease to 77.3% in 2026/27, and also indicated an acceleration in the introduction of the proposed fiscal anchor in the MTBPS. However, Hamilton believes that the statement must explain how this trajectory will be maintained amid changing economic conditions.

The economic outlook has become more complex. In February, the Treasury projected growth of 1.6% in 2026, whereas the South African Reserve Bank projected 1.2% in September and raised its interest rate to 7.25% in response to renewed inflationary pressure caused by global supply shocks. The official unemployment rate reached 33.6% in the second quarter. Hamilton notes that growth at such levels leaves little room to solve the employment problem in South Africa.

Despite this, there have been positive signals from rating agencies. In May, S&P maintained a positive outlook and affirmed South Africa's BB foreign currency rating, while Moody's upgraded its outlook to positive and confirmed the Ba2 rating. Nevertheless, Hamilton warns that further improvement depends on actual implementation, and a positive outlook does not yet mean a rating upgrade.

While a stronger fiscal position can boost confidence, Hamilton argues that businesses may still hesitate due to unreliable water supply or electricity connection delays. He believes that fiscal discipline and practical reform must advance in parallel, with the MTBPS providing greater clarity on the government's choices. It is necessary for revenue assumptions to be realistic, new obligations to be adequately funded, and risks associated with state-owned enterprises to be clearly disclosed. Furthermore, Hamilton points to the need to improve expenditure efficiency while protecting priority spending.

Infrastructure investment is a central element of these efforts. Support from the World Bank for reforms in electricity, transport, and water underscores the link between functioning infrastructure, private investment, and employment. For investors, projects become viable when necessary permits are in place, procurement is credible, contractual obligations are clear, and repayment terms are sound. Hamilton advises the government to focus more on project preparation and the capacity of state institutions, while measuring progress against clear implementation commitments. Servicing must also be financed alongside new infrastructure investments.

Private sector participation can help, provided that risks and government obligations are transparently and appropriately distributed. Hamilton believes that simplifying licensing, predictability of administrative procedures, and timely payment of valid invoices could significantly impact, especially for small and medium-sized enterprises (SMEs). He argues that the government must improve expenditure management and tax administration before assuming that compliant businesses and households can continue to bear additional burdens.

In turn, businesses must make investment decisions based on sound commercial judgment rather than waiting for every economic problem to be fully resolved. Hamilton also calls for broader access to suitable financing, referencing the International Finance Corporation's work on supporting SME lending, trade, and supply chain finance, as well as business training and support. He believes that businesses should be helped to develop the financial information and managerial capabilities needed to use funds effectively. Some investments may increase efficiency under various conditions, while others depend on the completion of specific reforms. Where possible, Hamilton recommends phased capital deployment and setting clear criteria before further action.

The external environment also influences investment decisions. In the World Economic Forum's 2026 Global Risks Report, geopolitical confrontation was named the leading short-term risk, according to a survey of leaders and experts. Hamilton advises companies to analyze their exposure to trade risks, supplier concentration, and alternative market exit routes. Scenario planning is useful as it defines how a company will react to changing conditions and who has the authority to act.

Hamilton concludes that the MTBPS gives the government an opportunity to provide greater clarity on the direction of the economy and the necessary decisions to support investment. The government must implement reforms and improve the use of public resources, while businesses must manage risks, develop personnel, and invest where they can create sustainable value. He notes that the test in the coming months will be whether these commitments enable businesses to expand and employ more people.

Voluntary Pension Fund (VPF) as a Savings Option: Comparing Interest Rates with Deposits
Read more
www.aajtak.in

Voluntary Pension Fund (VPF) as a Savings Option: Comparing Interest Rates with Deposits

For working individuals, it is just as important to invest funds correctly as it is to save money for retirement. If you regularly contribute to the Employees Provident Fund (EPF), you can increase your savings through the Voluntary Pension Fund (VPF). Under this program, employees can contribute an amount in addition to the mandatory contribution to the PF. Currently, the EPF yields an annual interest rate of 8.25%. However, before increasing investments in VPF, it is necessary to understand tax issues, withdrawal periods, and whether this option meets your financial needs.

What is VPF and how does it work?

The Voluntary Pension Fund is a voluntary savings scheme linked to the Employees Provident Fund. Employees have the option to contribute more than their standard PF contribution. This allows for an increase in the total amount accumulated for retirement. The advantage is that the money is automatically deducted from the salary and deposited into the PF account, eliminating the need for additional monthly investments. Nevertheless, the main goal of VPF is long-term savings accumulation for retirement, not achieving high profits in a short time. The same interest rate as for EPF, set by the government, is applied.

Who might benefit from VPF?

VPF is particularly useful for employees who aim for regular long-term savings and do not wish to invest a significant portion of their savings in schemes dependent on stock market fluctuations. It may be interesting for employees who hold large sums in Fixed Deposits (FD), as one can compare the potential return of VPF with the return of FD after taxes, while considering the withdrawal conditions and tax rules of both instruments. VPF is also considered by employees approaching retirement, such as those aged 40 or 50, who want to regularly top up their fund, although the decision must be made considering the remaining time until retirement, current savings, and future expenses. Furthermore, for those who find it difficult to manage monthly personal investments, the automatic deduction of funds into VPF can help establish a saving habit. However, it should be remembered that if you have expensive debts, lack an emergency fund, or require large sums in the near future, these more pressing issues must be addressed first.

What does the limit of ₹2.5 lakh mean?

Before making additional contributions to VPF, it is important to understand a key tax rule. If both the employee and the employer contribute to the PF, tax on the interest related to the total annual employee contribution to EPF and VPF may exceed ₹2.5 lakh. This tax is not applied to the entire additional amount but to the interest associated with it according to established rules. It is important to note that the ₹2.5 lakh limit applies only to the employee's contributions and does not include the employer's contributions. If the employer does not make contributions to the employee's PF, a separate limit of ₹5 lakh may apply to the interest on the employee's contributions. The annual limit of ₹2.5 lakh is equivalent to approximately ₹20,833 per month. Nevertheless, the actual calculation must be based on the employee's total contribution for the entire financial year. The mandatory EPF contributions and the amounts contributed to VPF must be summed up to determine if the limit has been exceeded.

How is the tax calculated with an example?

Suppose the employee's total contribution for the financial year was ₹3 lakh, exceeding the ₹2.5 lakh limit by ₹50,000. This does not mean that tax will be levied on the entire ₹50,000. The tax calculation will be done according to the rules, based on the interest related to this additional contribution. Assuming the maximum employee tax rate is 30% and the interest rate is 8.25%, the post-tax return could be around 5.78%. This is an approximate calculation that does not include fees and other applicable factors. The actual tax will depend on the employee's status and prevailing regulations. Therefore, before contributing additional funds to VPF, one should not only look at the announced interest rate; one must understand what amount may be subject to taxation.

Are there tax benefits on funds contributed to VPF?

Automatic tax benefits on funds contributed to VPF are not provided. The benefit in the form of a deduction for the contribution depends on the chosen tax system and the relevant conditions for the employee. Therefore, before increasing investments, it is necessary to find out which tax system you report under and what deductions are available to you. It is important to distinguish between the tax on interest related to contributions and the deductions received at the time of investment; these two aspects should not be confused.

When can funds be withdrawn from VPF?

VPF funds are part of the EPF account, so they cannot be withdrawn at any time, like from a regular savings account. To withdraw funds, one must consider the current EPF rules, eligibility criteria, length of service, and reason for withdrawal. In October 2025, the Central Council of Trustees of the Employees Provident Fund (EPFO) approved a simplification of partial withdrawal rules and set the minimum service period for eligibility at 12 months. This structure provides for various needs, such as illness, education, marriage, housing, and special circumstances.

Popular