SIP Formula to Achieve Millionaire Status: How to Accumulate Large Capital Through Regular Investments
Read more
Aaj Tak
www.aajtak.in

SIP Formula to Achieve Millionaire Status: How to Accumulate Large Capital Through Regular Investments

Despite ongoing fluctuations in the stock market, which are also reflected in the mutual fund market, investors aiming to build significant capital are advised to maintain their investments and not succumb to panic from market instability. Investing through SIP (Systematic Investment Plan) over the long term is considered a profitable solution capable of making a person a millionaire if the correct strategy is followed.

The possibility of accumulating over one million rupees is examined, starting with monthly contributions of just 10,000 rupees.

Tensions in the Middle East, caused by the conflict between the US and Iran, have impacted global stock markets, leading to serious losses for some investors. However, most experts advise against stopping SIP during such fluctuations, as it is a long-term investment scheme that has historically yielded substantial profits for investors.

Market experts recommend starting new SIPs even amid volatility. By starting investments with a monthly contribution of 10,000 rupees, one can accumulate a capital of one million rupees, but this requires following a specific formula—using Step-up SIP. This strategy involves increasing the SIP amount by 10 percent or more annually, which ultimately leads to millionaire status.

Consider an example: if you start SIP with a monthly contribution of 10,000 rupees, assuming an annual increase of 10% and an average annual return of 20%, the fund will exceed one million rupees in 13–14 years. Calculations show that thanks to the annual 10% increase, the monthly contribution after 5 years will reach 14,600 rupees, and the total fund volume will be around 1.4–1.6 million rupees. Similarly, after 10 years, the monthly payment will grow to 23,500 rupees, increasing the total deposit amount to 4.5–5.5 million rupees. If this strategy continues, the monthly payment will reach 38,000 rupees after 14 years, and the total capital will be 1 million rupees.

In this one million rupee portfolio, the total amount invested will be approximately 3.8–4.2 million rupees, while the remaining significant portion will be the result of the power of compound interest, which plays a key role in long-term investing through SIP. SIP provided investors with returns within the range of 18–20%, and this return is the factor that allows one to become a millionaire. It is important to note that the calculations are based on the assumption of a 20% return and do not represent a guaranteed amount; the actual return may be higher or lower.

Similar stories

Sicredi expands financial guidance for members through digital platform
Read more
g1.globo.com

Sicredi expands financial guidance for members through digital platform

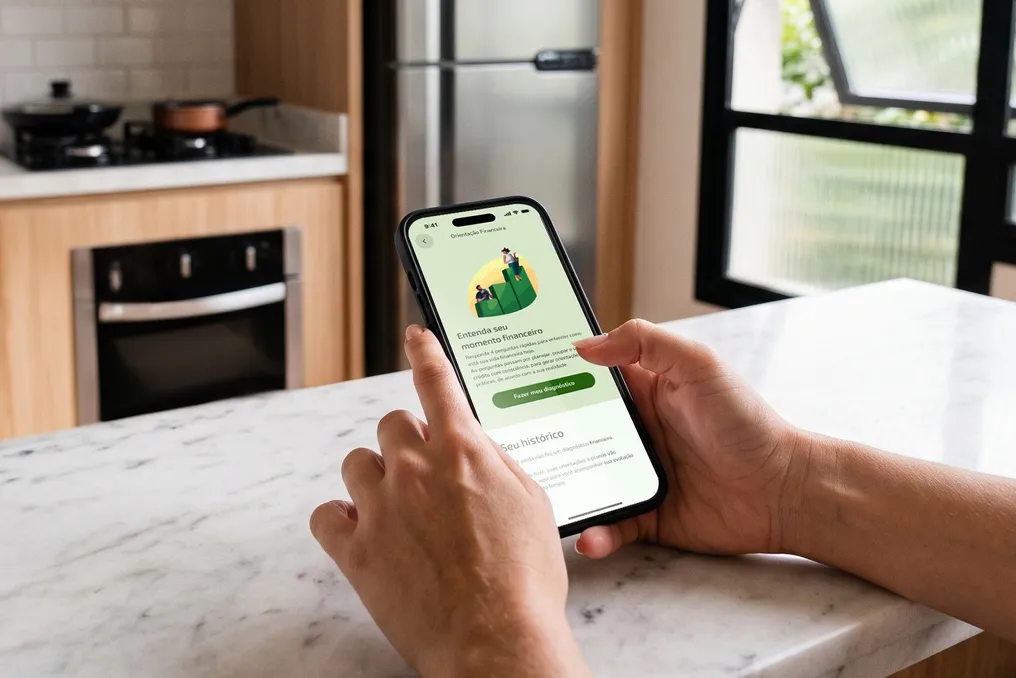
Sicredi has implemented its Financial Guidance initiative in the digital environment, aiming to increase support for its members both in managing their finances and in making more conscious decisions. This experience offers detailed analyses and personalized suggestions on topics such as investments, planning, and responsible credit use, accessible via the Sicredi X application, which has been progressively adopted by the members of this financial cooperative.

Previously, Financial Guidance was provided through business manager advice at Sicredi branches and via remote channels, such as WhatsApp, helping members reflect on their economic situation and define action plans according to their goals and needs. The recent addition of this initiative to the digital environment has already accumulated over 140 thousand services and reached members across the entire national territory.

How it works

The digital process begins with a questionnaire consisting of four questions, focused on how the member organizes their finances, their ability to manage unforeseen events, and their relationship with financial obligations. Based on these answers, the system determines which area requires the most focus at the moment: whether it is financial planning, savings, or conscious credit.

Subsequently, the member receives a tailored plan and can select between two or three practical actions to implement. Recommendations include educational materials, such as videos, courses, and financial organization tools. Furthermore, the journey integrates products and services from an educational perspective, explaining simply how each solution can contribute to financial well-being. The user also has the option to monitor their progress, access past guidance, and redo the diagnosis whenever there is a change in their financial condition.

Machado commented that very positive results have been observed among those who used Financial Guidance, whether in person or remotely. He highlighted the adoption of healthier financial habits and the strengthening of the bond with Sicredi. According to him, with this initiative, the institution reaffirms its commitment to supporting more thoughtful financial choices and generating lasting value for members and the communities where it operates. He emphasized that financial well-being is a continuous process, and access to appropriate information and guidance is crucial to converting intention into action.

To strengthen financial well-being, the new digital tool was created to help members analyze their financial life and identify opportunities for improvement in a practical and personalized way. Some daily practices can support more conscious decisions:

  • Know your financial reality: Constantly monitor income, expenses, and commitments to understand money usage and find opportunities for improvement.
  • Have an emergency reserve: Maintaining a financial reserve provides greater security to deal with unexpected events without harming the budget or long-term plans.
  • Define clear goals: Setting goals provides direction to financial decisions and facilitates maintaining discipline over time.
  • Use credit consciously: Before taking on new debts, it is essential to evaluate the real need, the repayment capacity, and the impact of the decision on the budget.
  • Review habits periodically: Since financial planning is a continuous cycle, reviewing expenses, priorities, and goals helps keep finances aligned with different life stages.
Brokers predict 53% growth in HFCL Limited shares; company showed 296% return over the year
Read more
www.aajtak.in

Brokers predict 53% growth in HFCL Limited shares; company showed 296% return over the year

Although it is impossible to predict which stock on the stock market will bring significant profit to investors, there are numerous examples of such success. One such example is the shares of HFCL Limited, which became a multibagger stock for its investors in 2026, providing them with substantial returns.

Currently, brokers are optimistic about this stock, expecting the HFCL Share Price to grow by 53%.

HDCL Ltd is an Indian technology company engaged in the design, development, and manufacturing of telecommunication equipment, fiber optic cables, and other related electronic equipment. The company's shares are listed on both the Bombay Stock Exchange and the National Stock Exchange. As of the last trading day on Monday, the HFCL Share Price closed at 268.81 rupees, and the company's market capitalization is 41130 crore rupees.

HFCL shares proved to be a multibagger instrument for investors in 2026. This is evidenced by the return received by investors. Specifically, on the last working day of last year, December 31, 2025, the HFCL Share Price was 67.79 rupees, and currently, it has yielded a return of 296.53% for investors.

Nuvama Institutional Equities expressed confidence in HFCL Limited and raised its target price from the previous 380 rupees to 410 rupees. Compared to the current price, the broker sees potential for this multibagger asset to grow by 53 percent.

The brokerage firm Nuvama not only expressed confidence in HFCL shares by significantly increasing the target price but also advised investors to purchase these shares and include them in their portfolio. Nuvama confirmed its 'Buy' rating for HFCL, citing HFCL's excellent second-quarter results as well as a positive outlook.

The broker noted that the company's record quarterly performance, high revenue forecasts, growing orders, strong cash flow, and improved working capital position were the reasons for raising the initial target price. In the second quarter of the 2027 fiscal year, HFCL's revenue grew by 144% compared to the previous year, and EBITDA demonstrated a year-on-year growth of 231%.

Voluntary Pension Fund (VPF) as a Savings Option: Comparing Interest Rates with Deposits
Read more
www.aajtak.in

Voluntary Pension Fund (VPF) as a Savings Option: Comparing Interest Rates with Deposits

For working individuals, it is just as important to invest funds correctly as it is to save money for retirement. If you regularly contribute to the Employees Provident Fund (EPF), you can increase your savings through the Voluntary Pension Fund (VPF). Under this program, employees can contribute an amount in addition to the mandatory contribution to the PF. Currently, the EPF yields an annual interest rate of 8.25%. However, before increasing investments in VPF, it is necessary to understand tax issues, withdrawal periods, and whether this option meets your financial needs.

What is VPF and how does it work?

The Voluntary Pension Fund is a voluntary savings scheme linked to the Employees Provident Fund. Employees have the option to contribute more than their standard PF contribution. This allows for an increase in the total amount accumulated for retirement. The advantage is that the money is automatically deducted from the salary and deposited into the PF account, eliminating the need for additional monthly investments. Nevertheless, the main goal of VPF is long-term savings accumulation for retirement, not achieving high profits in a short time. The same interest rate as for EPF, set by the government, is applied.

Who might benefit from VPF?

VPF is particularly useful for employees who aim for regular long-term savings and do not wish to invest a significant portion of their savings in schemes dependent on stock market fluctuations. It may be interesting for employees who hold large sums in Fixed Deposits (FD), as one can compare the potential return of VPF with the return of FD after taxes, while considering the withdrawal conditions and tax rules of both instruments. VPF is also considered by employees approaching retirement, such as those aged 40 or 50, who want to regularly top up their fund, although the decision must be made considering the remaining time until retirement, current savings, and future expenses. Furthermore, for those who find it difficult to manage monthly personal investments, the automatic deduction of funds into VPF can help establish a saving habit. However, it should be remembered that if you have expensive debts, lack an emergency fund, or require large sums in the near future, these more pressing issues must be addressed first.

What does the limit of ₹2.5 lakh mean?

Before making additional contributions to VPF, it is important to understand a key tax rule. If both the employee and the employer contribute to the PF, tax on the interest related to the total annual employee contribution to EPF and VPF may exceed ₹2.5 lakh. This tax is not applied to the entire additional amount but to the interest associated with it according to established rules. It is important to note that the ₹2.5 lakh limit applies only to the employee's contributions and does not include the employer's contributions. If the employer does not make contributions to the employee's PF, a separate limit of ₹5 lakh may apply to the interest on the employee's contributions. The annual limit of ₹2.5 lakh is equivalent to approximately ₹20,833 per month. Nevertheless, the actual calculation must be based on the employee's total contribution for the entire financial year. The mandatory EPF contributions and the amounts contributed to VPF must be summed up to determine if the limit has been exceeded.

How is the tax calculated with an example?

Suppose the employee's total contribution for the financial year was ₹3 lakh, exceeding the ₹2.5 lakh limit by ₹50,000. This does not mean that tax will be levied on the entire ₹50,000. The tax calculation will be done according to the rules, based on the interest related to this additional contribution. Assuming the maximum employee tax rate is 30% and the interest rate is 8.25%, the post-tax return could be around 5.78%. This is an approximate calculation that does not include fees and other applicable factors. The actual tax will depend on the employee's status and prevailing regulations. Therefore, before contributing additional funds to VPF, one should not only look at the announced interest rate; one must understand what amount may be subject to taxation.

Are there tax benefits on funds contributed to VPF?

Automatic tax benefits on funds contributed to VPF are not provided. The benefit in the form of a deduction for the contribution depends on the chosen tax system and the relevant conditions for the employee. Therefore, before increasing investments, it is necessary to find out which tax system you report under and what deductions are available to you. It is important to distinguish between the tax on interest related to contributions and the deductions received at the time of investment; these two aspects should not be confused.

When can funds be withdrawn from VPF?

VPF funds are part of the EPF account, so they cannot be withdrawn at any time, like from a regular savings account. To withdraw funds, one must consider the current EPF rules, eligibility criteria, length of service, and reason for withdrawal. In October 2025, the Central Council of Trustees of the Employees Provident Fund (EPFO) approved a simplification of partial withdrawal rules and set the minimum service period for eligibility at 12 months. This structure provides for various needs, such as illness, education, marriage, housing, and special circumstances.
Popular