Record prices for luxury real estate recorded in Mumbai: one house valued at 152 crore rupees
Read more
Aaj Tak
www.aajtak.in

Record prices for luxury real estate recorded in Mumbai: one house valued at 152 crore rupees

The luxury real estate market in Mumbai is witnessing a new record for the sale of expensive houses. In one residential complex, the average cost of a house reached 152 crore rupees. This project is called Naman Xana and is located in the Versova area of Mumbai.

In the first half of the 2026-27 financial year, specifically from April to September 2026, three houses were sold in this project for a total of 456 crore rupees. Thanks to this, Naman Xana ranked first among the ten best luxury residential projects in Mumbai by the average price per house.

According to the Lighthouse Luxury report, this analysis is based on property registration data, specifically statistics from the Chief Inspector of Registration of Maharashtra (IGR). The report indicates that demand for luxury homes in prestigious areas of Mumbai remains strong, with prices in some selected projects reaching very high levels.

Although Naman Xana led in the average price per house, Godrej Trilogy Seafront won the category of total sales volume. In this project, also located in Versova, 54 houses were sold from April to September 2026, totaling 1,199 crore rupees. The average price per house here was approximately 22.2 crore rupees.

Oberoi Elysian ranked second in this list. Over the six-month period, 67 houses were registered for a total of 899 crore rupees, while Rustomjee Crown saw 51 houses sold for a total of 622 crore rupees.

Prestige Nautilus also entered the list of luxury residential projects in Mumbai. From April to September 2026, 18 houses were sold there for a total of 571 crore rupees, corresponding to an average price of about 31.7 crore rupees, and ranked second in the rating by average cost.

Lodha The Park registered the highest number of sales—76 houses, totaling 563 crore rupees, with an average house price of about 7.4 crore rupees. In Runwal Raaya, 36 houses were sold during the same period for a total of 550 crore rupees.

According to the report, a total of 496 houses were sold across the top 10 luxury residential projects in Mumbai over six months. The total value of these transactions reached 6,116 crore rupees. The project ranking was based on the total value of registered transactions, not the number of houses.

The statistics clearly demonstrate significant differences in prices between various projects in the Mumbai luxury real estate market. While the average price per house in Naman Xana was 152 crore rupees, in Godrej Reserve, this figure was significantly lower—around 5.7 crore rupees.

Similar stories

Expert discusses the role and functioning of the insurance market in the economy of Uzbekistan
Read more
nuz.uz

Expert discusses the role and functioning of the insurance market in the economy of Uzbekistan

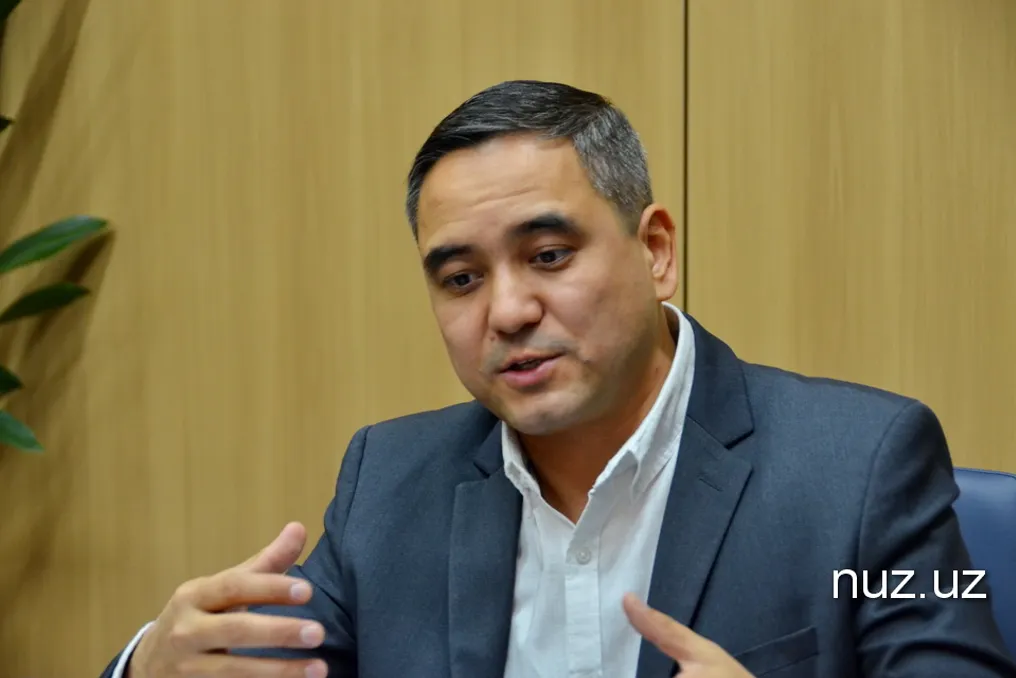
Although most citizens are familiar with the word 'insurance,' few realize how broadly the insurance system covers various aspects of the economy and society. Umid Khudayberdiyev, founder of three insurance companies and a specialist with over twenty years of experience in this field, presented methods and technologies for operating the insurance market during the FINNEXT Asia forum in Tashkent on November 19. Previously, he worked at the State Insurance Supervision under the Ministry of Finance of the Republic of Uzbekistan.

Drawing on his extensive experience, Umid Khudayberdiyev explained that the economy is a complex system where the interests of the state, business, and citizens constantly intersect, and therefore it is acutely in need of protection. Insurance acts as a key tool for financial defense, contributing to the stability of the national economy, attracting investment, and reducing the burden on the state budget.

The benefits of insurance are distributed among three main groups: the population, which receives stability and protection from sudden financial losses; the state, which partially assumes the function of protecting the population by evenly distributing economic risks; and investors.

When asked about the low level of financial literacy in the country, which leads to the neglect of insurance, Umid Khudayberdiyev suggested correcting the term, pointing to insufficient awareness. He noted that people intuitively understand physical risks, but abstract financial and insurance systems require specialized knowledge.

With the active development of digital platforms in Uzbekistan, such as Gov.uz, MyID, and banking fintech services, the number of fraudulent schemes is also growing. Insurance can protect both individuals and companies from such threats, especially when there is a lack of knowledge in the field of financial protection.

He also mentioned products such as cyber insurance and document insurance. Furthermore, although the state guarantees deposits up to 200 million soms, special insurance products exist for amounts exceeding this limit to help protect citizens' funds from fraudsters.

A transparent mechanism for protecting investor funds is critically important for attracting foreign capital. A serious investor is primarily concerned with the preservation of their capital, not just potential profit. In developed countries, decisions are made collegially, and proof of transaction security is required before major projects.

The reliability of the economy is assessed through the maturity of the insurance market: how quickly it pays compensation and covers domestic risks, rather than relying solely on reinsurance abroad. Since the state cannot provide unlimited guarantees, banks, funds, and insurance companies must independently offer quality assets.

It was noted that there is an imbalance where the banking sector outpaces the insurance sector. However, the insurance industry is actively catching up with the support of banks and the state. Since 2008, three key laws on mandatory insurance have been adopted in Uzbekistan: motor vehicle owner liability, employer liability insurance, and carrier liability insurance.

In the field of Islamic finance, Islamic insurance (Takaful) is entering the market, meeting citizens' needs to preserve savings in accordance with their values, which is an important element of harmonious market development.

High birth rates in Uzbekistan are viewed as a huge resource and the country's main advantage, despite the enormous strain this places on infrastructure and the economy. The expert emphasized that the country is coping with these challenges, and with systemic investments in education and human capital, Uzbekistan can significantly surpass other countries both economically and socially.

Regarding poverty, which may increase with a large population, it is noted that the relevant ministry is systematically working on this issue. The fight against poverty is a comprehensive state program that includes construction, education, and social support. The President rightly noted the achievement of the level of Turkey and Europe in the speed and quality of construction.

The financial sector is interested in developing insurance because commercial banks bear risks associated with non-performing loans (NPL) or damage to collateral. Without insurance coverage, the entire risk falls directly on the bank. Therefore, the development of the insurance sector is critically important for banks.

The main goal of insurers is not only to generate income but also to deeply integrate insurance into the economy and society of Uzbekistan. It was concluded that without insurance, movement is possible, but high levels of development are unattainable.

Risks are a brake on economic growth. The absence of insurance protection forces businesses to avoid risky operations due to fear of losses. The economy is forced to slow down and spend resources on liquidating the consequences of technological and natural disasters. Net economic growth is defined as real progress minus losses from all types of risks.
Moody's rates South Africa's fiscal policy as positive for credit rating, maintaining upgrade prospects
Read more
iol.co.za

Moody's rates South Africa's fiscal policy as positive for credit rating, maintaining upgrade prospects

The latest statement on the Medium-Term Budget Policy Statement (MTBPS) was viewed by Moody's as positive from a credit rating perspective for South Africa. This conclusion leaves open the possibility of a rating upgrade in the coming months.

Investec Chief Economist Annabel Bishop commented on Moody's positive credit outlook, pointing to several market factors currently influencing the rand exchange rate. Previously, the rand recovered some of the gains made in October. Global risk appetite has decreased due to investor concerns over inflated valuations of artificial intelligence-related technology stocks. Meanwhile, the US dollar strengthened, and the price of gold fell to approximately $4016 per ounce, matching levels from July and one year ago. For a country that remains heavily reliant on gold exports, this movement is significant.

Concurrently, oil prices exceeded $115 per barrel of Brent crude. Renewed tensions in the Middle East, including increased Iranian attacks on tankers and reduced traffic through the Strait of Hormuz, led to record freight rates and unusually low inventories.

Furthermore, the approach of winter in the Northern Hemisphere adds another source of demand uncertainty, even if the expected El Niño pattern may mitigate some heating needs.

Fuel Price Reduction and Narrowing Rate Differentials

The rise in oil prices intensified concerns about imported inflation. In response, the MTBPS announced a temporary reduction in fuel excise duties: 3 rand per liter for diesel and 1.50 rand per liter for petrol, from November 4 to December 1, with subsequent smaller reductions until early January. The IOL Fuel Price Support program indicates that this R10 billion intervention is aimed at supporting drivers and businesses without disrupting the overall fiscal trajectory.

This relief should help offset routine monthly price adjustments and limit the transmission of these changes into inflation and interest rates. Meanwhile, the interest rate differential between South Africa and the United States is expected to begin narrowing. The US is still viewed as a country that will raise rates this year, whereas no such move is anticipated from South Africa. This narrowing creates some downward pressure on the rand. However, the currency has not fallen as sharply as often seen during full-blown risk-off episodes. Volatility remained lower than in previous years, especially against the euro and pound, indicating that positive domestic conditions provided a partial buffer.

Moody's Observations

Annabel Bishop reported that Moody's assigned South Africa a BB rating and upgraded the outlook to positive in May. A rating upgrade remains likely within approximately eighteen months, provided the fiscal trajectory is maintained. The agency noted that the recent statement demonstrated continued fiscal consolidation despite tighter monetary policy and weaker nominal GDP growth, which negatively impacted some indicators.

Moody's forecasts that the debt-to-GDP ratio will peak and then decline to 84.9 percent within two years, down from 86.8 percent last year. The projected consolidated budget deficit improved due to revenue surpluses. At the same time, Moody's points to South Africa's persistent low debt service capacity: the share of revenue dedicated to interest payments remains higher than in most peer countries. High debt servicing costs continue to be the main constraint on public finances.

On the positive side, the agency sees potential for increased budget revenue, which is the main driver of consolidation. Improved tax receipts and an 11 percent increase in debt collection since the beginning of the year support this view. It is important to note that MTBPS forecasts show growth in the consolidated primary surplus even with plans to increase infrastructure spending. Moody's considers this a particularly noticeable commitment to discipline.

Broader Stabilization Picture

IOL Business

Reports published around the MTBPS highlighted the same themes. The Ministry of Finance adjusted its 2026 growth forecast downwards to 1.2 percent, reflecting the oil shock and tougher global conditions. Nevertheless, debt stabilized for the first time in nearly two decades at 78.4 percent of GDP, and the primary surplus is expanding. A draft legislation on a fiscal anchor was released for public discussion, signaling an intent to ensure long-term discipline. Savings exceeding 38 billion rand were identified in the medium term through efficiency measures and loss reduction.

These domestic changes help explain why the recent weakness of the rand was more moderate than in previous periods of global caution. Markets appear to differentiate between temporary external pressure and a fiscal structure that continues to move in the right direction. In the long term, oil prices, gold prices, US rate expectations, and overall risk sentiment will remain dominant short-term factors affecting the exchange rate. Domestically, the fuel excise relief should help curb inflationary pressure, while the MTBPS assured investors that consolidation remains on track.

Under the base case scenario, the gradual removal of structural constraints, moderate growth, and sustained fiscal discipline should support greater rand stability in the medium term. The positive rating trajectory and improved revenues create a solid foundation. Currently, Moody's message is straightforward: the past budget update was positive for the credit rating. The prospect of a rating upgrade mentioned earlier this year remains valid, provided the government continues to follow the consolidation path set by the Minister of Finance. This is a constructive signal for investors and the broader economy while global conditions remain unstable.

Deadline for vehicle licensing fee payment in Tocantins is this Friday (30)
Read more
g1.globo.com

Deadline for vehicle licensing fee payment in Tocantins is this Friday (30)

Vehicle owners whose license plates end in 3, 4, 5, 6, 7, 8, 9, and 0 have until this Friday, the 30th, to pay the annual licensing fee in the state of Tocantins. This deadline was established by the State Department of Traffic (Detran/TO).

Detran announced that there will be no in-person service on Friday (30) due to the optional holiday related to Public Servant Day, as stipulated by Decree No. 7.254. However, the services necessary for licensing remain accessible online.

For vehicles with plates ending in 1 and 2, the due date was September 30th. According to Detran/TO, the schedules are governed by Ordinance No. 26/2026, published in the State Official Gazette (DOE) No. 6,996, and comply with Resolution No. 110/2000 of the National Traffic Council (Contran).

How to make the payment

The cost of the licensing fee is R$ 79.83 for all types of vehicles. If the licensing is overdue, an additional fine charge of R$ 36.86 will be applied.

This licensing procedure is mandatory for the issuance of the electronic Vehicle Registration and Licensing Certificate (CRLV-e). Without payment of the corresponding fee, the driver is unable to obtain this document, which is essential for the vehicle's circulation and requires annual renewal.

Popular