How compliance helps farms secure financing
Read more
Food For Mzansi
foodformzansi.co.za

How compliance helps farms secure financing

For farmers, adhering to tax legislation and sound financial management is not merely an administrative formality; these aspects can determine a business's ability to obtain financing, government support, and open new market opportunities.

Commercial sunflower producer Happy Letseza and agricultural finance consultant Sibo Mole from Molo Consulting shared practical advice on how to organize financial reporting, accounting, and compliance for securing farm financing. Furthermore, the South African Revenue Service (SARS) outlines tax provisions and requirements specific to agricultural enterprises.

The combined experience of these specialists demonstrates why farmers should view financial records, tax compliance, credit management, and supporting documentation as an integral part of building a financially sound agricultural enterprise.

One of the most crucial conditions for both tax compliance and access to financing is a clear understanding of the farm's financial position. Mole advises maintaining regular financial records throughout the year, rather than trying to reconstruct activities at the time of filing a tax return or a financing application. Monthly record-keeping must document income and expenses, providing the necessary information for preparing annual financial statements.

Letseza notes that farmers approaching commercial lenders are preferably required to have annual financial statements for the last three years. Additionally, farmers should avoid mixing personal and business finances. The farm must have a dedicated bank account through which all farm income and expenses pass. Mixing household expenditures with farm operations complicates the determination of real business efficiency and can complicate tax and financial reporting.

Mole insists: 'Everything related to the farm must be in the farm's business accounts. The farm must have its own bank account.'

Farm assets constitute a significant part of its financial standing. Farmers are obliged to maintain an up-to-date asset register covering items such as tractors, vehicles, equipment, machinery, and livestock. Mole emphasizes that the register must reflect the actual assets on the farm and contain identification information, if applicable, such as vehicle numbers, purchase dates, and cost.

Livestock must also be properly registered, and inventory must be conducted regularly. An accurate asset register is useful for preparing financial reports, insurance, tax returns, and financing applications, especially if the assets may be part of an assessment conducted by a lender.

This register must include: movable assets (vehicle numbers, serial numbers, purchase dates, and current value); fixed infrastructure (buildings, irrigation systems, and permanent fencing records); and biological assets (regular livestock count records, breeding lines, and mortality tracking).

Sound financial accounting is also important for income tax, as it allows farmers to distinguish between farm income and legitimate business expenses, and provides data for calculating taxable income. Mole warns farmers against reducing agricultural business to informal operations.

He argues: 'Taxation of farms is a very specialized regime. An entire schedule of the Income Tax Act is written specifically for farming.' This underscores the need to work with an accountant or tax specialist who understands agriculture and the specific tax provisions applicable to agricultural enterprises.

SARS provides special VAT incentives for eligible farming enterprises. A registered farmer seller can purchase certain agricultural resources at a zero rate provided that the relevant requirements and permits are met. These goods include animal feed, veterinary medicines, fertilizers, pesticides, plants, and seeds used for cultivation.

Farmers must comply with SARS requirements, including having a valid registration notice and the necessary permit. A valid tax invoice must also be issued, and the goods must fall under the relevant provisions of Value Added Tax Act No. 89 of 1991. SARS also provides a six-month VAT period category D for eligible farming enterprises with agricultural turnover not exceeding R1.5 million over a consecutive 12-month period. Farmers should clarify their specific circumstances with SARS or a qualified tax professional.

Diesel fuel can constitute high operating costs for farmers, so proper record-keeping is critical when claiming diesel fuel reimbursement. Mole stresses that farmers cannot rely solely on refueling receipts. Farmers must keep the necessary records and logs, and understand the current SARS requirements for registration and applications. Since the system and requirements for diesel fuel reimbursement can change, farmers should check the latest procedure with SARS or their tax specialist.

It is necessary to ensure that your farm records comply to receive the necessary tax relief. A registered farmer seller can purchase certain agricultural resources at a zero rate. Furthermore, SARS provides a six-month VAT period category D for eligible farming enterprises with turnover not exceeding R1.5 million.

Tax compliance is only one part of being ready for financing. Farming enterprises must monitor the currency of their registration information. Farmers operating through a company must maintain compliance with the Companies and Intellectual Property Commission (CIPC), including annual reports and beneficial ownership information. Mole warns that non-compliance with CIPC can lead to company liquidation.

Employers must also fulfill their obligations to employees, including applicable labour norms, Unemployment Insurance Fund (UIF), Pay As You Earn (PAYE) withholding tax, and Compensation for Occupational Injuries and Diseases Act No. 130 of 1993 (Coida). Moreover, the farmer's credit profile can directly affect access to financing. Letseza emphasizes the importance of timely payments and maintaining good relationships with creditors.

Letseza says: 'Pay your creditors on time, maintain a good credit history, and ensure every transaction on the farm is recorded.' Mole adds that lenders often assess both the business's financial health and the owner's personal credit history.

Proof of the farmer's legal right to operate on the land is another important aspect of financing readiness, whether it is a certificate of title or a valid lease agreement. When applying for financing, Letseza advises farmers to act proactively and give lenders enough time to assess their business. Letseza recommends: 'Apply early so that if the bank requests additional information, you have time to provide it.'

Farmers must clearly explain what the money will be spent on. Instead of simply requesting a large sum, Mole advises linking the financing request to a specific business need, such as a tractor, irrigation system, livestock, or infrastructure. Mole concludes: 'The amount you need is determined by what the farm needs.' He believes that financial reports should be viewed as part of the farm's infrastructure, alongside machinery, fencing, or vehicles. As he puts it: 'Banks already know: no books, no credit. Financial reports are the farm's infrastructure.'
Similar stories

How to improve a farm's credit rating and ensure access to financing
Read more
foodformzansi.co.za

How to improve a farm's credit rating and ensure access to financing

Access to financial resources allows farmers to acquire necessary resources, invest in equipment, expand production, or cover seasonal cash needs. However, having a viable farming enterprise does not guarantee automatic approval of a loan application.

It is crucial for farmers to understand the concept of credit risk and demonstrate the ability to manage and repay debt when preparing to obtain financing. Sibo Molo, an agricultural consultant and director of Molo Consulting, Brendan Jacobs, Head of Agribusiness at Standard Bank, and Zama Sangweni, an agricultural economist at Absa, highlight several aspects that should be considered before approaching a lender.

Farmers can obtain various types of financing, including overdrafts, business loans, asset financing, revolving credit lines, trade finance, and working capital loans. Sangweni notes that each type of loan has a specific purpose, and farmers must ensure that the chosen instrument aligns with the intended financing goals.

She emphasizes: 'The type of loan must actually match the purpose and lifespan of the investments being financed.' For example, an overdraft is better suited for managing short-term cash flow fluctuations, whereas a long-term loan can be used for large projects such as farm expansion or infrastructure work.

Sangweni explains that a loan makes sense when it is used to create future value and promote business growth. If the enterprise constantly takes out loans just to cover operational losses or monthly expenses, this is often seen as a sign of poor cash flow management.

In such cases, alternative funding sources such as grants, venture capital, blended finance, or development finance may be more appropriate.

There are different types of financing: short-term instruments (overdrafts, trade finance) are ideal for purchasing raw materials and covering seasonal cash gaps. Medium- and long-term instruments (asset financing, term loans) are intended for acquiring machinery, livestock, and developing infrastructure.

A farmer's creditworthiness is determined not only by the financial performance of the agricultural business itself. Molo points out that lenders may also consider the personal credit history of the farm owner or company directors.

Molo notes: 'Your personal credit history is very important when you apply for business financing.' Unpaid personal accounts, whether retail or mobile, can negatively affect the credit profile and potentially hinder access to financing.

Sangweni adds that this is especially relevant for new or small businesses with limited operating history, as lenders may examine the owner's financial behavior alongside the business activities. As the business matures, the focus increasingly shifts to the enterprise's own financial efficiency and credit profile.

Therefore, farmers are advised to check their credit records before applying, identify any outstanding accounts or disputes, and settle legitimate debts where possible. Credit committees in South Africa assess your compliance, financial management, and operational risks before disbursing funds. It is recommended to conduct an audit of your business against these 25 key criteria to assess your application readiness.

Jacobs states that lenders analyze both general risks associated with agriculture and the risks of the specific business seeking financing. Industry risk considers factors affecting the agricultural sector, including the commodity and the farmer's geographical area of operation. At the same time, counterparty risk examines the management team and business practices.

Sangweni believes that the fundamental question for a financier is the business's ability to sustainably repay debt. 'We look at cash flow generation. We also look at business profitability.'

Lenders may also consider the current level of debt, credit history, collateral, and the purpose of the financing.

One of the most important points before taking out a loan is determining a realistic amount of debt the farm can afford. Sangweni advises farmers not to base their borrowing needs solely on the amount the lender is willing to offer.

'The starting point is always the cash flow, not the amount the lender is willing or able to provide,' she states. Farmers must understand what free cash flow remains after covering operating expenses, taxes, and existing debt obligations. They must also assess whether they can make payments during periods of reduced business activity or in case of an agricultural downturn. Sangweni recommends stress-testing the business before taking on additional commitments.

Agriculture is subject to various risks that can affect income and repayment ability. These include crop losses, commodity price fluctuations, labor issues, changes in margins, and high capital expenditures. Jacobs insists that farmers must be aware of these risks and demonstrate what measures they are taking to manage them.

He says: 'Financial management practices must demonstrate effectiveness in farming practices, understanding data, actions taken for risk management and mitigation, and proactive cost control.' For instance, a farmer requesting financing for production must be able to explain expected yield, production costs, market conditions, and what precautions are available if conditions change.

Droughts, floods, disease outbreaks, and other climatic events can directly impact farm production and income. This makes climate resilience an increasingly significant aspect of farmers' financial risk management. Jacobs notes that agricultural financiers understand the cyclical nature of agriculture and susceptibility to external shocks. He adds that 'proactive communication aids planning,' and banks also consider the farmer's ability to cope with difficulties and withstand financial adversity.

Consequently, farmers should consider investments and management methods that reduce vulnerability, such as water-efficient irrigation, appropriate insurance, diversifying production where commercially viable, and robust contingency planning.

Sound financial reporting is one of the cornerstones of responsible credit management. Molo advises farmers to keep regular records and maintain accurate financial statements.

He emphasizes: 'Financial reporting is necessary for obtaining financing.' An accurate asset register is also important, which should reflect assets such as tractors, vehicles, and livestock, with up-to-date identification information. Such records help the farmer understand the business's value and can be useful when assessing collateral or security.

Sangweni reports that lenders may require annual financial statements, management reports, bank statements, cash flow forecasts, company registration documents, tax information, and details of financing use. She explains: 'If the information is more complete and accurate, it creates a better opportunity for the lender to actually assess your application and make an informed decision.'

Farmers should also separate their farm and personal finances and regularly record transactions instead of trying to reconstruct records when the financing application deadline approaches.

Farmers with little or no business credit history can start by demonstrating that the business is capable of meeting its financial obligations. Sangweni recommends maintaining proper financial documentation, separating personal and business finances, keeping transaction records, and demonstrating a stable cash flow.

She asserts: 'It is very important to create proof that the business can responsibly manage financial obligations.'

When necessary, smaller credit lines also allow the business to build a repayment track record before taking on large amounts of debt.

When considering a loan, farmers should look beyond just the interest rate. Sangweni notes that the total cost of borrowing can include interest, transaction fees, and other charges, as well as the frequency and terms of repayment. 'They need to understand the total cost of borrowing.'

Farmers must determine whether interest rates are fixed or variable, understand what will happen to payments if rates rise, and consider how payments will affect cash flow if income is delayed. The repayment term must also align with the financing goal. Sangweni warns: 'You cannot use a long-term investment financing tool for a short-term project.'

Borrowing can promote growth, but excessive debt can limit the farm's ability to operate and respond to changing conditions. Sangweni highlights several warning signs, including repeatedly taking on new debt to pay off old debt, persistent cash shortages, rising monthly obligations, and an increasing proportion of income directed towards debt servicing.

She concludes: 'When debt begins to restrict operational flexibility or strategic decision-making, it is often time to review the financial structure.' Farmers should also be cautious if borrowed funds are used for purposes other than those specified in the financing application.

Responsible borrowing means using debt for purposes that strengthen the business, not just postponing existing financial problems. Sangweni notes that successful enterprises tend to use credit to generate future income, including productive assets, expansion, technology upgrades, or additional working capital linked to proven growth potential.

Jacobs similarly advises farmers to use reliable data when preparing financing applications, rather than relying on overly optimistic projections. 'Be transparent with your financier; it builds trust and relationships,' advises Jacobs.

Collateral can be a serious obstacle for farmers who do not own traditionally accepted assets. However, the absence of collateral does not mean the farmer has no financing options. Sangweni says that farmers without collateral must strengthen other aspects of their applications. Farmers can also explore blended finance, development finance, and credit guarantee mechanisms if they suit them. Some financing structures place more emphasis on demonstrated cash flow generation and repayment ability than solely on assets.

Proper debt management begins before repayment problems arise. Farmers must closely monitor repayment schedules, avoid excessive commitments, and contact lenders if financial pressure is anticipated. Sangweni asserts: 'Missing payments is generally much more damaging than maintaining transparent relationships and communication before difficulties arise.'

Early communication can allow the farmer and the lender to assess available options before the situation becomes more difficult. Ultimately, credit management is more than just getting a loan; it is building a farming business capable of productively utilizing borrowed capital.

Experts at Agda Congress: Simply increasing production is not enough for agricultural success in South Africa
Read more
foodformzansi.co.za

Experts at Agda Congress: Simply increasing production is not enough for agricultural success in South Africa

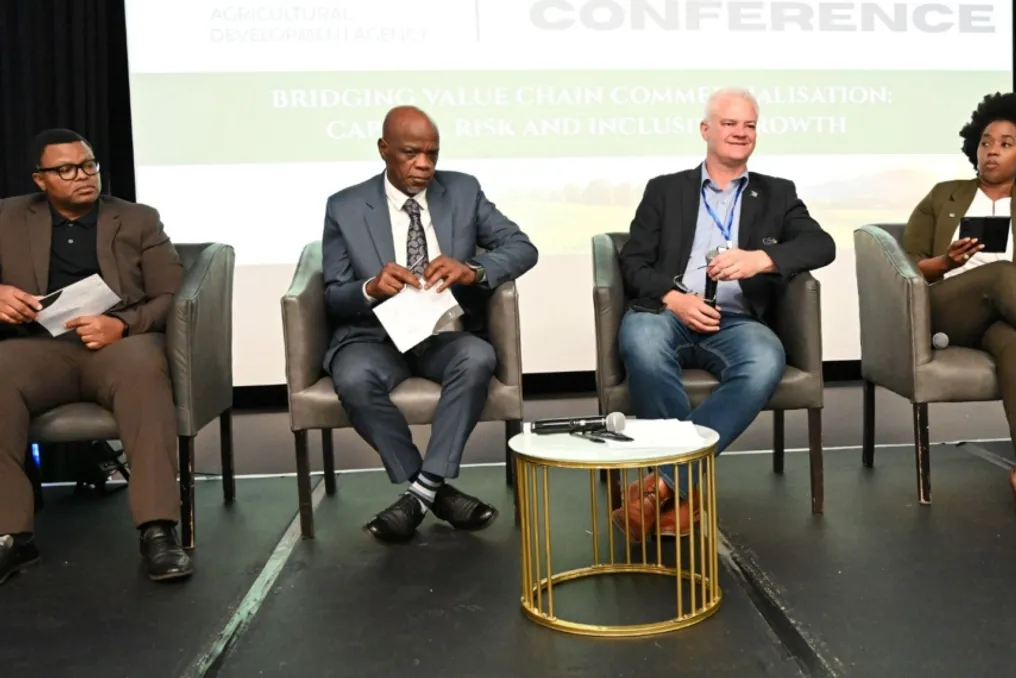
At the annual Agricultural Development Agency (Agda) congress in Boksbuur, Gauteng, experts emphasized that opening commercial opportunities for emerging farmers in South Africa's agricultural sector requires more than just increasing production volumes. It was noted that access to markets, long-term capital, agro-processing, and strengthening partnerships are vital.

Speakers highlighted the need to support smallholder farmers in transitioning to commercial agriculture, enhancing their competitiveness in global markets, and building stronger links between producers, processors, financiers, and buyers.

Vuyiswa Ramokgopa, a member of the Gauteng Provincial Executive Committee for Agriculture and Rural Development, stated that the African Continental Free Trade Area (AfCFTA) opens up prospects for agricultural exports, value addition, and agro-processing. She stressed that South Africa is already a significant player on the continent with a good foundation for further development.

Ramokgopa cited an example from the Southern African Development Community (SADC), where bananas produced in Mozambique are transported to Johannesburg for ripening before being returned to Mozambique and other markets. This case demonstrates the potential for expanding agro-processing and strengthening regional agricultural trade.

Furthermore, Ramokgopa called for greater recognition of the informal market, which accounts for about 60% of fresh produce trade in the country. She insisted that discussions on market access must include not only large retail chains but also informal traders who require support and skills development to participate more effectively in the agricultural value chain.

Regarding agricultural financing, Ramokgopa noted that the issue is not so much a lack of funds as it is limited access by farmers to information about available opportunities and the requirements of various institutions. She emphasized that farmers need to understand the requirements of financiers and establish commercially viable enterprises supported by reliable income, collateral, and strong business relationships. She also advocated for an increase in long-term capital, warning that agriculture cannot always meet the demands of investors expecting returns within five years.

Meanwhile, Dr. Tobias Doer, CEO of Grain SA, stated that South African farmers need to compete internationally by improving productivity and more effectively utilizing value-added market opportunities. He compared this to participating in international competitions, arguing that farmers need support to win.

Doer stressed that economic growth is critical for job creation and strengthening domestic demand, while international markets offer additional chances for agricultural producers. He advised grain producers to consider options beyond exporting raw commodities, including transforming grain into high-value animal protein products such as poultry, pork, and beef. According to him, if you compete with grain, you always remain in the commodity market, but if you compete in the animal protein market, you compete and earn in the premium market.

The President of the African Farmers Association of South Africa (Afasa), A. J. Mthembu, noted the strategic importance of agriculture despite rapid technological changes, as food production remains essential. He also pointed to opportunities to expand South Africa's product basket by cultivating a wider range of goods for domestic and international consumption, calling for sustainability amid changing markets.

Sizwe Dludla, an investment partner at the National Empowerment Fund (NEF), suggested that deeper integration of existing agricultural enterprises could help farmers utilize available resources more effectively. He pointed to the possibility of connecting disparate farming operations with established markets and ancillary businesses, such as linking processing plants with poultry producers and connecting farmers with school feeding programs. Dludla noted: 'The market exists, but it needs a certain specific quality, quality consistency, and financiers are ready to fund farmers to produce the required quality.'

He urged farmers, buyers, and financiers to work together to form an agricultural ecosystem that supports stable production and meets market demands.

Joanne Kotze, CEO of AgriSA, cautioned that financial and production resources alone will not be enough to ensure the success of emerging farmers. She stated that South Africa needs better mechanisms to help people transition from small-scale farming to sustainable commercial operations. Kotze also emphasized the importance of social structures, skills, partnerships, and collective responsibility in building a successful farming business. She reminded: 'The fact that you are a farmer does not give you the right to come to me and say: 'I need to borrow money from you',' stressing the need for farmers and financial institutions to understand their mutual obligations. She warned that focusing only on land, water, and finance while ignoring the relationships and support systems underpinning agricultural business can make farmers vulnerable to failure.

Popular