UAE Investments in the UK: Football Clubs, London Landmarks, and Billion-Pound Assets
Read more
Middle East Eye
www.middleeasteye.net

UAE Investments in the UK: Football Clubs, London Landmarks, and Billion-Pound Assets

The United Arab Emirates (UAE), one of the world's wealthiest nations, whose seven monarchies own sovereign wealth funds exceeding $2 trillion in assets, is actively investing globally. These investments, driven by oil revenues as well as finance, tourism, and gold trade, span banks, airports, and restaurant chains across North America, Europe, and other regions.

However, the partnership between the UAE and the UK faces unprecedented scrutiny. Under the UAE-UK Sovereign Investment Partnership, the UAE committed to investing nearly $30 billion between 2021 and 2026.

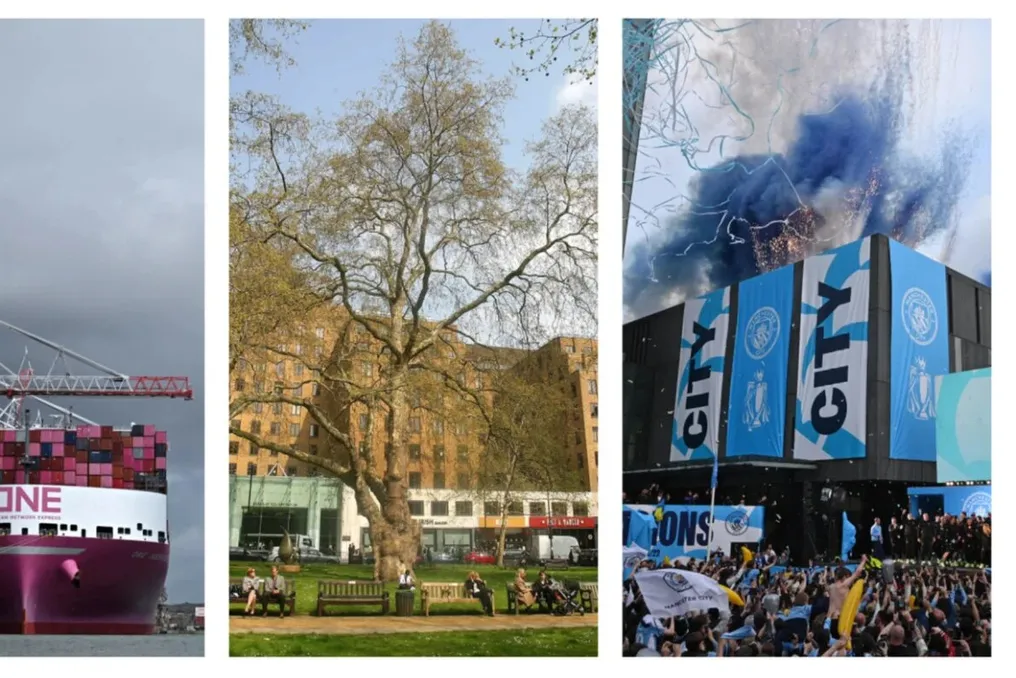
In September, it was revealed that Manchester City FC, owned by Emirati royalty and Vice President Sheikh Mansour bin Zayed Al Nahyan, violated 114 Premier League financial regulations by concealing over £830 million ($1.1 billion) in illicit funding. The club denies these allegations.

UK Prime Minister Andy Burnham found himself at the center of this scandal, as he served as Mayor of Manchester from 2017 until June, a period during which Emirati funds transformed both Manchester City and the city itself. Cooperation with the UAE became even more controversial due to the country's role in the civil war in Sudan, where it is accused of supporting the Rapid Support Forces—a paramilitary group whose mass killings, according to UN investigators, show 'signs of genocide.' The UAE rejects these claims.

Nevertheless, Burnham seeks to balance public backlash against the UAE with the constant influx of investment from the Persian Gulf, which, according to both the football club's defenders and the government, has contributed to economic growth. These disagreements have highlighted the significant share of British institutions owned by Abu Dhabi and Dubai—the wealthiest emirates and largest investors.

Similar stories

Rules for Selling Real Estate with a Mortgage in Dubai: Debt Transfer Options
Read more
www.khaleejtimes.com

Rules for Selling Real Estate with a Mortgage in Dubai: Debt Transfer Options

The owner of property in Dubai who has an outstanding mortgage loan and plans to sell the real estate before returning to their home country needs to know the relevant rules. The question arises whether the buyer can take over the remaining mortgage debt, if bank approval is required, and what the legal procedure is for transferring ownership and settling or transferring the loan.

According to Dubai legislation, since the property is located in Dubai, the Dubai Mortgage Law applies. The seller (mortgagor) is permitted to sell, gift, or otherwise dispose of the mortgaged property, or create any rights on it, only upon obtaining the consent of the mortgagee and provided that the buyer agrees to assume all the seller's obligations under the mortgage agreement. The mortgagee also has the right to stipulate that the seller and buyer will jointly be responsible for these obligations. This corresponds to Article 10 of Dubai Law No. 14 of 2008 on Mortgages in the Emirate of Dubai.

There are two main options available to consider.

Option 1: Selling the Property by Settling the Existing Mortgage

The property can be sold, and the proceeds used to fully repay the existing mortgage loan. The general sequence of practical steps is as follows:

  1. Obtain a Letter of Obligation from the Bank: It is necessary to request a document confirming the outstanding loan amount and the required amount to close the mortgage, including any applicable early repayment fees or other payments.
  2. Agree on Sale Terms: A sales contract is concluded with the buyer, taking into account the existence of the mortgage, and the repayment of the loan amount is arranged.
  3. Registration of the Transaction with the Dubai Land Department (DLD): DLD provides a service called 'Registration of Sale of Mortgaged Property'. Under this service, the seller and buyer visit the Real Estate Registration Centre office with the necessary documents. The transaction is first registered to protect the interests of both parties while the mortgage repayment process is underway.
  4. Repayment of the Outstanding Loan: The DLD procedure involves the use of manager's cheques, including a cheque in favor of the bank for the debt amount and a cheque in favor of the seller for the remaining sale amount, if any. After this, a letter from the bank confirming the release of the mortgage is obtained.
  5. Completion of Ownership Transfer: After the DLD provides the mortgage release letter, it finalizes the registration procedures for the sale and the removal of the mortgage. If the buyer is obtaining a new mortgage, the corresponding financing and mortgage registration procedures must be completed.

This procedure is particularly relevant if the buyer pays for the purchase with their own funds or receives separate financing, and the seller's existing loan is settled using the sale proceeds. Exact documents and payment terms should be agreed upon with the bank and the Real Estate Registration Centre before completing the transaction.

Option 2: Transferring Existing Mortgage Obligations to the Buyer

Alternatively, permission can be requested from the bank for the buyer to assume the current mortgage obligations, if they are willing. In this case, you must approach the bank with a proposal for the deal and request confirmation on whether the buyer can take over the existing loan. The bank may assess the buyer's financial situation and require updated or replacement financing documentation. Any transfer of ownership and associated mortgage obligations must be documented and registered in accordance with bank approval and DLD requirements.

Based on the above provisions and procedures, the possibility of selling the property before returning home can be considered. The most suitable path will depend on whether the bank allows the buyer to assume the existing loan or requires the loan to be repaid using the sale proceeds. Written confirmation from the bank regarding the proposed procedure should be obtained, and actions should be coordinated with the DLD or the Real Estate Registration Centre to finalize the transaction.

For further clarification, it is recommended to contact your mortgage lender and the DLD.

Applicable Provision: Dubai Law No. 14 of 2008 on Mortgages in the Emirate of Dubai.

Indians Prepare to Buy Foreign Real Estate: Survey Shows Investment Plans Range from $250k to $1 Million
Read more
www.aajtak.in

Indians Prepare to Buy Foreign Real Estate: Survey Shows Investment Plans Range from $250k to $1 Million

According to the Knight Frank-IREX Survey, 85% of Indian citizens planning to purchase property abroad intend to invest an amount ranging from $250,000 to $1 million. The most sought-after property types in the survey were apartments and condominiums. A 64% increase was also noted in the amounts sent from India for the purchase of foreign real estate.

Purchasing property abroad is becoming part of the capital management strategy for Indian investors. Goals range from generating rental income to expecting asset appreciation. A joint study by Knight Frank India and IREX found that 61% of respondents consider rental income and capital gains as the main reasons for buying foreign real estate.

According to the 'Keys Beyond Borders' report by Knight Frank India and IREX, the volume of funds directed by Indian residents towards purchasing foreign real estate in the 2025-26 financial year reached $52.87 billion, representing an annual growth of 64%. In the previous financial year (2024-25), this amount was $32.282 billion. This growth occurred against a backdrop of an overall 2% decrease in remittances abroad under the Liberalised Remittance Scheme (LRS).

Despite the increase in the amount allocated for property purchases, the share of these funds in the total volume of international remittances remains relatively small—around 1.8%. Nevertheless, the survey statistics indicate a growing interest among respondents in investing in international real estate.

In the combined assets of the survey participants, real estate accounts for an average of 45%, of which 32% is domestic property and 13% is foreign property. Notably, about ten years ago, the share of foreign real estate in these respondents' portfolios was only around 5%. According to the report, 84% of respondents are already property owners abroad, while 16% are potential buyers planning to purchase property in the foreign market for the first time. This indicates that for the surveyed investors, foreign ownership is not just an option for living or vacationing, but also part of an asset diversification and investment strategy.

The interest of Indian buyers is spread across several markets. Prominent regions include the United Arab Emirates (UAE), Greece, Thailand, Portugal, Australia, the USA, the UK, Bali in Indonesia, Canada, and Malaysia. In addition to expected rental income and price growth, important factors in the decision to buy include opportunities for obtaining residency and 'golden visas'. Other motives include diversifying the investment portfolio, hedging currency risks, business expansion, tax benefits, children's education, and improving quality of life.

Regarding budget, 85% of respondents plan to invest between $250,000 and $1 million. Apartments and condominiums are the most popular property types, chosen by 69% of respondents. Next are villas and townhouses, preferred by 26% of respondents. Penthouses accounted for 4%, and branded residences for 1%. A trend regarding housing size was also identified: 76% of respondents are considering homes between 1,500 and 2,500 square feet. Of these, 49% prefer homes between 2,000 and 2,500 square feet, and 27% prefer those between 1,500 and 2,000 square feet.

The profile of people considering purchasing foreign real estate has also been revealed. 53% of respondents are business owners, traders, and industrialists. Corporate executives and working professionals make up 30%, and first-generation entrepreneurs account for 11%. Interestingly, about ten years ago, the share of corporate executives and working professionals among those interested in foreign real estate was only 7%, and now it has risen to 30%. Furthermore, 76% of respondents are aged between 35 and 50, which is considered an important age for capital formation, investment diversification, and long-term financial planning.

For Indians planning investments in foreign real estate, it is crucial to understand not only the investment opportunities but also the relevant regulations. The report emphasizes the need to comply with the Reserve Bank of India's Liberalised Remittance Scheme (LRS), the Foreign Exchange Management Act (FEMA), and the applicable tax norms of the country where the investment is made. It should be noted that the data presented in the report reflects buyer intentions, not actual transactions, and the survey sample does not cover all Indians.
Popular