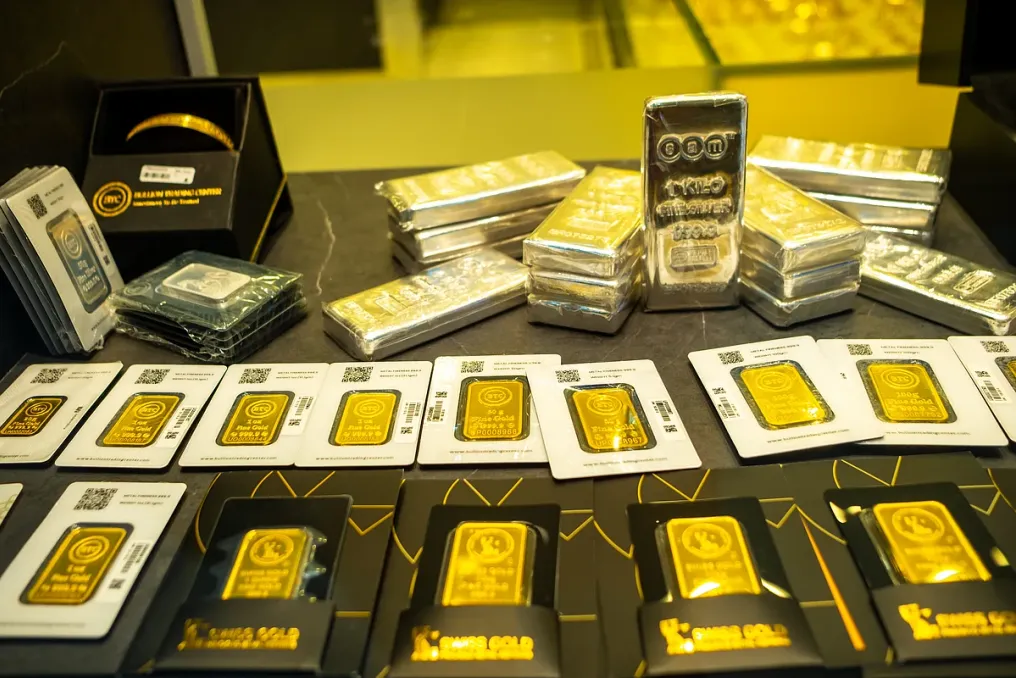
Gold prices in Dubai rose slightly on Tuesday morning, recovering after a slight decrease recorded on Monday evening.
According to data from Dubai Jewellery Group, the prices for 24K, 22K, and 21K pure gold were 505.75 dirhams, 468.25 dirhams, and 449.0 dirhams per gram, respectively.
The spot gold rate increased by 0.8 percent, reaching $4199 per ounce, against the backdrop of falling oil prices. Markets awaited US inflation data to gain new signals regarding the trajectory of Federal Reserve interest rates.
Naim Aslam, Investment Director at Zaye Capital Markets, noted that the recovery in gold prices reflects improved conditions for precious metals. This is linked to lower energy prices and a relatively weak US dollar, which reduces pressure on bullion.
He stated that President Donald Trump's announcement of a proposed energy truce between Russia and Ukraine, as well as an agreement to increase supplies of Russian diesel fuel, contributed to the drop in oil prices. Lower energy costs may support gold by reducing expectations of tight monetary policy, but sustained price growth will depend on whether Treasury bond yields and the dollar exchange rate continue to fall.
Geopolitical uncertainty remains another important factor stimulating demand for gold as a safe haven. Aslam added that despite President Trump's announcement of an immediate energy truce, ongoing attacks on energy infrastructure cast doubt on its implementation, leaving the possibility of further disruptions in global energy supplies.
In Aslam's view, any credible reduction in regional tension could temporarily weaken demand for safe-haven assets, especially if investors increase their share in stocks. Conversely, a resumption of energy supply disruptions or a deterioration in diplomatic negotiations could boost demand for gold. The critical distinction lies in whether lower oil prices will lead to a sufficient decrease in inflation expectations to outweigh any decline in geopolitical risk premiums.